
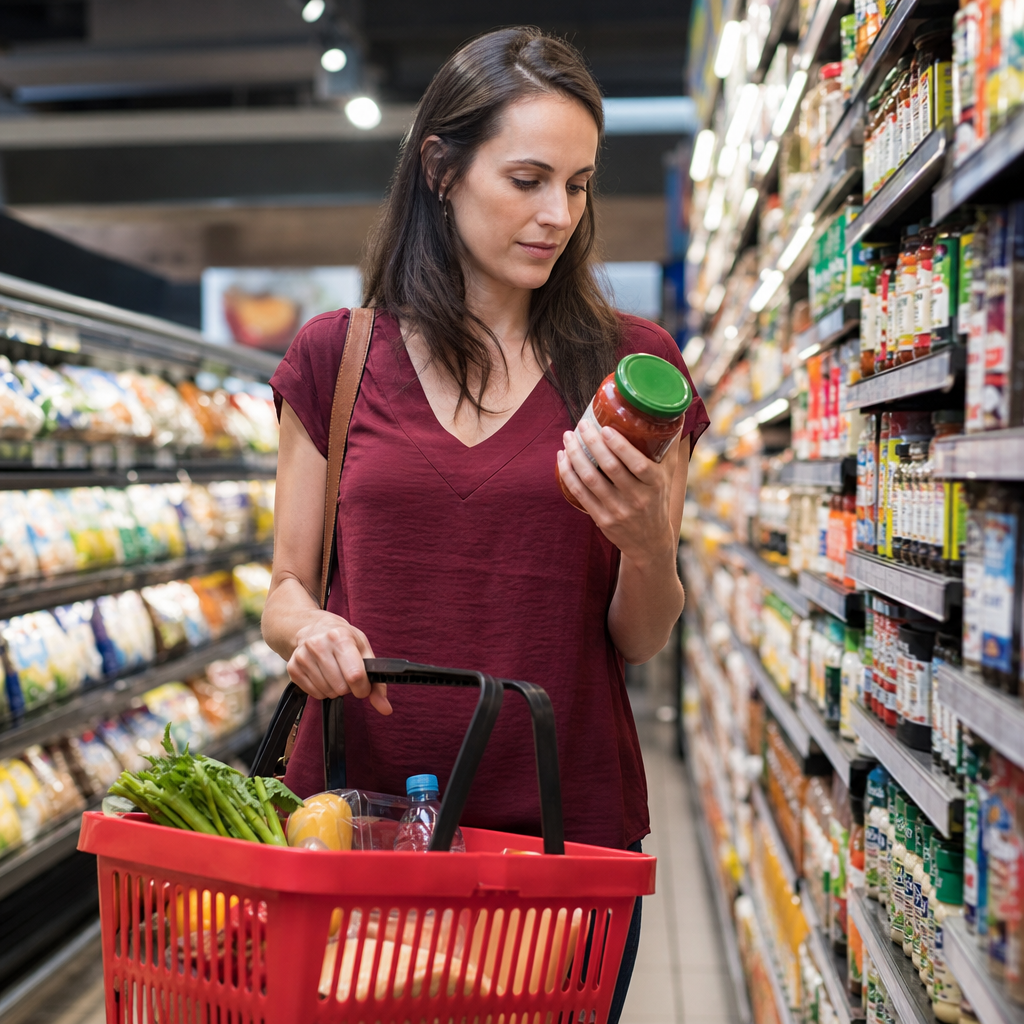
Utility maximization is the core idea economists use to explain how consumers make choices when money, time, and attention are limited. In plain terms, utility means satisfaction or perceived benefit, and maximization means choosing the combination of goods, services, or activities that delivers the highest total satisfaction within a budget. I have used this framework in teaching, pricing analysis, and consumer research, and it remains one of the most practical models in economics because it translates everyday tradeoffs into clear logic. Whether someone is deciding between rent and travel, coffee brands at a supermarket, or hours spent working versus relaxing, utility maximization provides a disciplined way to model the decision.
The concept matters because consumer choices shape demand, and demand influences prices, production, wages, and policy outcomes. When economists estimate how people react to taxes, subsidies, inflation, discounts, or product quality changes, they usually start from the assumption that households are trying to get the most value from constrained resources. That assumption does not mean people calculate equations in a store aisle. It means their behavior can often be described as if they compare benefits and costs and choose the best available option. This insight sits behind demand curves, cost of living indexes, welfare analysis, marketing strategy, and public policy design.
Several key terms define the framework. Preferences describe how a consumer ranks alternatives. A budget constraint shows what combinations of goods the consumer can afford at given prices and income. Marginal utility is the extra satisfaction from one more unit of a good. Diminishing marginal utility means each additional unit typically adds less satisfaction than the previous one. An indifference curve represents bundles that provide equal satisfaction, while the consumer optimum occurs where the highest attainable indifference curve touches the budget line. For discrete choices, economists often express the same logic through expected utility, random utility, or revealed preference, depending on the problem and data.
This hub article covers the full miscellaneous landscape around utility maximization: the standard model, graphical intuition, behavioral complications, uncertainty, intertemporal choice, labor supply, digital goods, policy applications, and common criticisms. If you want a concise answer, here it is: economists model consumer decisions by assuming people have ordered preferences, face constraints, and select the feasible option that yields the greatest utility. The rest of the article explains how that simple statement becomes a powerful tool for analyzing real markets and real human behavior.
The standard consumer choice model
The standard model begins with three ingredients: preferences, income, and prices. Preferences are assumed to be complete and transitive. Complete means a consumer can compare any two bundles, such as two books and one lunch versus one book and two lunches. Transitive means if bundle A is preferred to bundle B, and bundle B is preferred to bundle C, then bundle A is preferred to bundle C. These assumptions allow economists to represent preferences with a utility function, such as U(x,y), where x and y are quantities of two goods. The utility numbers themselves are not the point; the ranking is.
The budget constraint captures scarcity. If income is M, the price of good x is Px, and the price of good y is Py, then affordable bundles satisfy Pxx + Pyy ≤ M. Consumers cannot usually choose everything they want, so optimization matters. In graphical terms, the budget line shows all combinations that exactly exhaust income, and points below it are affordable but leave some money unspent. In most textbook cases with locally non-satiated preferences, the optimum lies on the budget line because more of at least one good is preferred to less.
The classic solution equates the marginal rate of substitution to the price ratio. The marginal rate of substitution is the rate at which a consumer is willing to trade one good for another while keeping utility unchanged. At an interior optimum, MRS = Px/Py. In plain language, the consumer keeps reallocating spending until the subjective value of the last dollar spent is balanced across goods. If the last dollar spent on streaming provides more satisfaction than the last dollar spent on restaurant meals, the consumer shifts spending toward streaming until the advantage disappears.
Economists also use a marginal utility per dollar rule. A utility-maximizing consumer chooses quantities so that MUx/Px equals MUy/Py across goods, assuming smooth preferences and interior solutions. This rule is especially useful for intuition. Imagine a shopper with ten dollars choosing fruit. If one extra apple gives 8 units of marginal utility and costs two dollars, while one extra orange gives 6 units and costs one dollar, the orange delivers more utility per dollar. A rational reallocation pushes purchases toward oranges until the ratios align or one choice hits a corner solution.
Indifference curves, substitution, and income effects
Indifference curve analysis gives the model visual power. Each curve shows bundles the consumer values equally, and curves farther from the origin represent higher utility when both goods are desirable. The slope of the indifference curve is the marginal rate of substitution, while the slope of the budget line is determined by relative prices. The best affordable bundle is where the budget line is tangent to the highest reachable indifference curve. That tangency condition explains why relative prices influence consumption even when income is unchanged.
When price changes, economists decompose the effect into substitution and income effects. The substitution effect reflects the fact that a lower price makes a good relatively cheaper, encouraging the consumer to substitute toward it. The income effect reflects the change in purchasing power created by the price change. If gasoline prices fall, a household can buy the same weekly fuel with less money, freeing cash for groceries, savings, or leisure. For normal goods, both effects move in the same direction after a price decrease. For inferior goods, the income effect works in the opposite direction.
The Slutsky decomposition and Hicksian demand formalize this distinction and are standard tools in microeconomics. In applied work, the distinction matters because it tells us whether policy changes alter choices mostly through incentives or through effective income. A transit subsidy, for example, lowers the out-of-pocket price of commuting and may increase transit use partly because buses become relatively cheaper than driving and partly because riders feel less financially constrained. The framework is not abstract bookkeeping; it is how economists separate mechanisms when evaluating tax credits, coupon programs, or energy rebates.
| Concept | Definition | Everyday example | Why economists care |
|---|---|---|---|
| Marginal utility | Extra satisfaction from one more unit | The first slice of pizza feels better than the fourth | Helps explain how consumers allocate spending |
| Diminishing marginal utility | Each added unit usually gives less benefit | A second streaming subscription adds less value than the first | Supports downward-sloping demand |
| Substitution effect | Change caused by relative prices | Buying chicken when beef becomes expensive | Measures response to incentives |
| Income effect | Change caused by altered purchasing power | Lower rent leaves more money for other goods | Shows how affordability changes demand |
From theory to demand curves and market evidence
Utility maximization is valuable because it generates testable demand behavior. If a consumer maximizes utility subject to a budget, demand for a normal good typically falls when its price rises, all else equal. Aggregating many households produces market demand, which businesses and policymakers use constantly. Retailers infer demand elasticity from scanner data. Central banks watch how households respond to inflation. Tax authorities estimate whether cigarette taxes reduce purchases enough to improve public health. The theoretical model gives these exercises structure and discipline.
In practice, economists estimate demand with household surveys, loyalty card data, online clickstreams, and natural experiments. A supermarket chain can observe how cereal sales change when one brand gets a temporary discount and use that variation to infer substitution patterns. Digital platforms run A/B tests to measure willingness to pay or responsiveness to bundle offers. Researchers often connect these findings to utility-based models such as discrete choice logit, nested logit, or Almost Ideal Demand System specifications. These methods are widely used because they convert observed choices into interpretable measures of preferences, elasticities, and welfare changes.
Revealed preference is another important bridge between theory and data. Rather than asking consumers how much satisfaction they get, economists look at what they actually choose when facing prices and budgets. If a household repeatedly buys generic pain relievers over branded versions despite similar active ingredients, the revealed preference may indicate strong price sensitivity or low perceived quality differences. Revealed preference analysis has limits, especially when information is incomplete, but it is often more reliable than self-reported intentions because choices involve real tradeoffs.
Behavioral complications and bounded rationality
The standard model is powerful, but real consumers do not always behave like frictionless optimizers. Behavioral economics documents present bias, loss aversion, mental accounting, default effects, and limited attention. These patterns do not destroy utility maximization; they refine it. In many modern models, utility includes reference points, self-control costs, or probability weighting. I have seen this clearly in subscription markets, where cancellation friction keeps customers enrolled even when stated satisfaction is low. A strict textbook model may predict exit, while a behavioral model captures inertia and search costs.
Consider present bias. People may prefer saving for retirement in the abstract but postpone enrollment because immediate consumption feels more salient than future security. Automatic enrollment in pension plans dramatically raises participation, a result documented in influential work by Brigitte Madrian and Dennis Shea. The lesson is not that utility theory fails. It is that the utility function may include time inconsistency, and the choice environment affects outcomes. Similarly, loss aversion means a ten-dollar surcharge can deter behavior more than a ten-dollar discount encourages it, even when the arithmetic is the same.
Bounded rationality also matters when decisions are complex. Consumers shopping for health insurance or mobile plans often face too many attributes to compare easily. They use heuristics such as choosing the middle option, sticking with incumbents, or focusing on one salient price. Economists respond with models that allow search costs, noisy optimization, or rational inattention. These approaches preserve the central idea that choices respond to incentives while acknowledging that cognition is scarce. For policy and business, that nuance matters because simplifying information can improve decision quality as much as lowering prices.
Uncertainty, time, and the value of nonmarket choices
Many consumer decisions involve uncertainty. Expected utility theory models choices over risky outcomes by weighting utility by probabilities. Buying insurance is the classic example. A risk-averse consumer may pay a premium above expected monetary loss because the utility cost of a rare catastrophic event is large. Portfolio choice, deductible selection, warranties, and medical treatment decisions all fit this framework. Prospect theory challenges some assumptions, especially around small probabilities and losses, but expected utility remains the benchmark used in finance, public economics, and industrial organization.
Intertemporal choice extends utility maximization across time. Consumers decide not only what to buy, but when to buy, save, borrow, or work. Economists model this with discounting: present utility is weighted more heavily than future utility. The Euler equation links current and future consumption, interest rates, and patience. In real life, this explains why lower borrowing costs can increase present spending, why high inflation can pull purchases forward, and why retirement saving depends on both income and self-control. Durable goods such as cars, appliances, and housing are especially sensitive to intertemporal tradeoffs.
Utility maximization also applies to labor supply and household production. People choose between leisure and income, between market services and do-it-yourself work, and between paid employment and caregiving. Gary Becker’s household production framework showed that families combine time and purchased inputs to produce commodities such as meals, child development, and clean living spaces. This is one reason wage changes can alter behavior beyond the workplace. If a parent’s hourly wage rises, the opportunity cost of time spent on home tasks rises too, potentially increasing demand for childcare, prepared food, or cleaning services.
Modern applications, limitations, and why the model endures
Today, utility maximization helps explain choices involving digital goods, platforms, and data. Consumers compare subscription bundles, ad-supported services, privacy settings, app ecosystems, and algorithmic recommendations. The price may be zero in cash terms, but the constraint includes time, attention, personal data, and switching costs. When users stay on a video platform for hours, economists do not assume every minute is welfare enhancing. They ask whether design features exploit biases, whether users face lock-in, and whether observed engagement reflects genuine preference satisfaction or manipulated choice architecture. That distinction is central in current antitrust and consumer protection debates.
The model also has clear limitations. Utility is not directly observable. Preferences can be unstable, socially shaped, or context dependent. Distribution matters: a policy that raises total utility in theory may still be unfair if benefits flow mainly to affluent households. Some choices are collective, moral, or identity based in ways simple budget models miss. Environmental decisions illustrate this well. A consumer may buy an electric vehicle partly for fuel savings, partly for status, and partly from ethical concern about emissions. A useful economic model should accommodate all three motives rather than force a narrow monetary story.
Even with these limitations, utility maximization endures because it is parsimonious, flexible, and empirically productive. It gives economists a common language for consumer behavior across groceries, healthcare, housing, education, entertainment, and labor decisions. It clarifies what changes when prices move, when income shifts, when information improves, or when institutions alter incentives. Most importantly, it turns messy human tradeoffs into analyzable patterns without claiming people are perfect calculators. If you are building your economics foundation, keep this model at the center, then explore the related articles in this hub to see how it connects to demand, welfare, game theory, and behavioral economics.
Frequently Asked Questions
What does utility maximization mean in economics?
Utility maximization is the idea that consumers try to get the greatest possible satisfaction from the choices available to them, given limits such as income, prices, time, and attention. In economics, “utility” does not usually mean happiness in a broad philosophical sense. It refers more specifically to the perceived benefit or value a person gets from consuming a good, using a service, or choosing one activity over another. “Maximization” means selecting the bundle of options that delivers the highest total benefit without exceeding the consumer’s constraints.
This framework is useful because it gives economists a structured way to model decision-making. Rather than assuming people buy randomly, utility maximization assumes they compare trade-offs. A consumer might ask, implicitly or explicitly, whether spending another dollar on coffee creates more satisfaction than spending that same dollar on streaming, transportation, or lunch. The model does not require perfect emotions or perfect lives; it simply assumes people make choices in ways that reflect their preferences under scarcity.
That is why utility maximization remains one of the most practical tools in economics. It helps explain everyday behavior such as bargain hunting, subscription choices, brand switching, and responses to price changes. Even when real people are not perfectly rational, the model still provides a powerful baseline for understanding how consumers allocate limited resources across competing wants.
How do budget constraints affect consumer decisions?
A budget constraint represents the limit on what a consumer can afford. It is one of the most important parts of utility maximization because preferences alone do not determine choices. A person may prefer luxury travel, premium groceries, and the newest technology, but income and prices restrict which combination is actually possible. The consumer’s problem is therefore not just to choose what they like most in the abstract, but to choose the most preferred bundle they can realistically afford.
Economists often describe this as a trade-off between different goods and services. If the price of one item rises, buying more of it may require giving up some amount of another item. For example, if rent consumes a larger share of income, the household may have less room for dining out, entertainment, or savings. In that sense, every spending decision has an opportunity cost. Utility maximization works by comparing the expected satisfaction from each possible use of limited resources and then shifting spending toward the mix that yields the highest total value.
Budget constraints also help explain why consumer behavior changes when income changes or prices move. A raise may allow someone to buy higher-quality products or simply consume more of what they already value. A price increase may push them toward substitutes. This is one reason the model is so important in pricing analysis and consumer research: it connects preferences to real market behavior by recognizing that all choices happen under constraint.
What is marginal utility, and why is it important?
Marginal utility is the additional satisfaction a consumer gets from consuming one more unit of a good or service. This concept is central to utility maximization because most decisions are made at the margin. Consumers rarely decide whether they want “all coffee” or “no coffee” in life. More often, they decide whether one more cup, one more subscription, or one more purchase is worth the cost compared with the next best alternative.
In many cases, economists assume diminishing marginal utility, which means each additional unit of a good tends to provide less extra satisfaction than the previous one. The first slice of pizza when you are hungry may be highly satisfying, the second still enjoyable, and the fifth much less valuable. This matters because it helps explain why consumers diversify their spending rather than putting their entire budget into a single good. As the extra benefit from one item falls, another use of money may offer more value at the margin.
The practical rule in consumer theory is that utility is maximized when the consumer allocates spending so that the marginal utility per dollar is balanced across goods, subject to the budget constraint. In plain terms, a rational consumer keeps shifting spending until the last dollar spent on each category delivers roughly comparable value. That principle is extremely useful for understanding how people react to promotions, product bundles, and relative price changes, and it remains one of the clearest ways economists model real-world choice.
Does utility maximization assume consumers are perfectly rational?
No. In its standard form, utility maximization assumes consumers have preferences, face constraints, and make choices that are generally consistent with those preferences. That does not mean they perform advanced calculations, possess full information, or always make flawless decisions. The model is an abstraction, designed to simplify reality so economists can identify patterns in behavior and make testable predictions.
In practice, real consumers are influenced by habits, emotions, framing effects, social pressure, limited attention, and imperfect information. Behavioral economics has shown many cases where actual decisions depart from the idealized version of rational choice. People may procrastinate, overvalue immediate rewards, stick with default options, or make inconsistent choices across similar situations. These findings are important, but they do not make utility maximization useless. Instead, they refine it and help economists understand where the basic model works well and where it needs adjustment.
The reason the framework remains so widely used is that it still captures an essential truth: people make trade-offs when resources are scarce. Even when decision-making is messy, consumers usually reveal priorities through what they choose, what they delay, and what they give up. For teaching, forecasting, and analyzing pricing or demand, utility maximization provides a disciplined starting point. Behavioral insights can then be layered on top to create a more realistic picture of consumer choice.
Why is utility maximization still relevant for pricing analysis and consumer research?
Utility maximization remains highly relevant because it gives businesses, researchers, and economists a practical way to interpret how consumers respond to prices, product features, and competing offers. At its core, the model says that people compare the value they expect to receive with the resources they must give up. That logic is directly applicable to pricing strategy, demand estimation, product positioning, and market segmentation.
For example, when a company changes a price, it is changing the trade-off the consumer faces. If the price rises, the product must justify a greater sacrifice of money relative to alternatives. If the price falls, the product may deliver stronger value per dollar and attract more buyers. Utility-based thinking also helps explain substitution effects, brand loyalty, bundling behavior, and willingness to pay for convenience, quality, or status. In consumer research, it supports the design of surveys, choice experiments, and segmentation models that try to measure what people value most.
Perhaps most importantly, utility maximization is relevant because it is flexible. It can be applied not only to goods and services, but also to time use, digital attention, subscription decisions, and lifestyle trade-offs. Modern consumers are constantly allocating limited money, time, and cognitive bandwidth across many options. The utility framework remains one of the clearest ways to model those choices, which is why it continues to be such a durable and practical tool in economics and applied market analysis.