
Revealed preference theory explains how economists infer what people value by observing the choices they actually make under real constraints. Instead of asking consumers what they prefer, the theory examines purchases, tradeoffs, and rejected alternatives to identify preference orderings consistent with behavior. In practical terms, if a household buys apples instead of oranges when both are affordable, that choice reveals a preference for apples in that situation. The idea sounds simple, but it became one of the most important tools in modern microeconomics because it shifted analysis from stated intentions to observable decisions.
The concept is most closely associated with Paul Samuelson, who formalized it in the late 1930s as a way to study consumer demand without relying on unobservable psychological utility. Key terms matter here. A budget set is the collection of bundles a consumer can afford at given prices and income. A chosen bundle is the option selected from that set. A revealed preference occurs when selecting one affordable bundle implies it is at least as preferred as other affordable bundles left unchosen. Weak and strong axioms of revealed preference then test whether a pattern of choices can be rationalized by stable preferences.
This matters well beyond textbook diagrams. I have used revealed preference logic in pricing reviews, retail assortment analysis, and policy evaluation because actual behavior often contradicts surveys. Consumers say they want low prices, for example, yet repeatedly pay premiums for convenience, brand trust, or lower search costs. Transportation planners infer values of time from commuting choices. Digital platforms estimate substitution between subscription tiers from upgrade and churn data. Public economists study labor supply, savings, and take-up of benefits through observed actions rather than self-reports. As a hub topic within economics, revealed preference theory connects consumer choice, welfare analysis, demand estimation, behavioral economics, game theory, and empirical market design.
Core idea: how choices reveal preferences
At its core, revealed preference theory starts with a disciplined question: given what a person could have chosen, what does the observed choice imply? Suppose a consumer has $20, apples cost $2, and oranges cost $4. If the consumer buys a bundle with eight apples and one orange instead of six apples and two oranges, economists say the chosen bundle is revealed preferred to the alternative, because both were affordable and only one was selected. This does not mean apples are always preferred to oranges. It means that under that price-income situation, the entire chosen bundle ranked above the forgone option.
That distinction is crucial. Preferences are not revealed in a vacuum; they are revealed relative to opportunity sets. Prices, income, quality differences, and available information shape what can be inferred. In practice, analysts build demand systems from many observed choices across changing budgets. If choices satisfy consistency conditions, they can be represented as if generated by utility maximization. This is why revealed preference theory became foundational: it provides an observable route from data to theory. Rather than assuming preferences and deriving choices, it uses choices to test whether coherent preferences could explain them.
Samuelson’s original formulation emphasized the weak axiom of revealed preference. If bundle A is chosen when bundle B was affordable, then B should not later be chosen when A is affordable, at least not under identical conditions, because that would generate a direct contradiction. Later work, especially by Hendrik Houthakker, extended the logic to stronger consistency conditions. In empirical work today, economists often discuss WARP, SARP, and GARP. These acronyms are not mere jargon. They define increasingly flexible tests for whether observed behavior is internally coherent, even when choices span many goods and many budget situations.
Weak, strong, and generalized axioms in plain language
The weak axiom of revealed preference, or WARP, rules out simple two-way contradictions. If a shopper chooses basket A when basket B was affordable, the shopper should not choose B in another observation when A is still affordable. WARP is intuitive and easy to apply, but it can miss more complex cycles. A consumer might choose A over B, B over C, and then C over A across different occasions. No single pair violates WARP directly in each observation, yet the full pattern can still be inconsistent with stable utility maximization.
The strong axiom, SARP, addresses these chains by prohibiting cyclical revealed preference relations. If A is revealed preferred to B, and B to C, then C cannot be revealed preferred to A. SARP is powerful but strict, especially when data include many observations and no allowance for indifference or measurement error. In applied consumer research, I rarely treat literal compliance with SARP as the final word because real data include scanner errors, stockouts, and timing noise. Still, SARP clarifies what full consistency means and gives a benchmark against which practical deviations can be judged.
The generalized axiom, GARP, is the workhorse in modern analysis because it allows weak inequalities and supports utility representation under broader conditions. GARP underlies Afriat’s Theorem, one of the central results in nonparametric demand analysis. The theorem shows that if a finite set of price-quantity observations satisfies GARP, then the data can be rationalized by a well-behaved utility function that is continuous, monotonic, and concave. That result is extraordinary because it lets economists test rationalizability without specifying a functional form like Cobb-Douglas or CES in advance.
How economists test revealed preference with data
In real datasets, revealed preference testing begins with observed prices and chosen bundles over multiple periods. For each observation, the analyst calculates what other bundles would have cost at those prices. If an earlier bundle would have been affordable in a later period but was not chosen, the algorithm records the implied preference relation. From there, graph methods or matrix methods search for violations of WARP, SARP, or GARP. The most widely cited practical route is Afriat efficiency analysis, which can also measure how far data depart from perfect consistency.
Afriat’s efficiency index is especially useful because few real-world datasets are perfectly clean. Households buy at different times, product qualities shift, and expenditures may not capture consumption exactly. The index asks how much budgets would need to be proportionally adjusted for choices to satisfy GARP. A score near one indicates choices are close to utility-maximizing behavior; lower scores suggest larger inconsistencies. In consumer panel work, this helps separate meaningful preference instability from harmless noise. It is one reason revealed preference methods remain relevant in empirical microeconomics rather than just in economic theory.
| Concept | What it tests | Main use | Typical limitation |
|---|---|---|---|
| WARP | Direct pairwise consistency | Simple contradiction checks | Misses longer cycles |
| SARP | No cyclical preferences | Strict rationality benchmarking | Harsh with noisy data |
| GARP | General consistency with utility maximization | Modern nonparametric testing | Needs careful expenditure measurement |
| Afriat Index | Degree of near-rationality | Applied datasets and diagnostics | Interpretation depends on data quality |
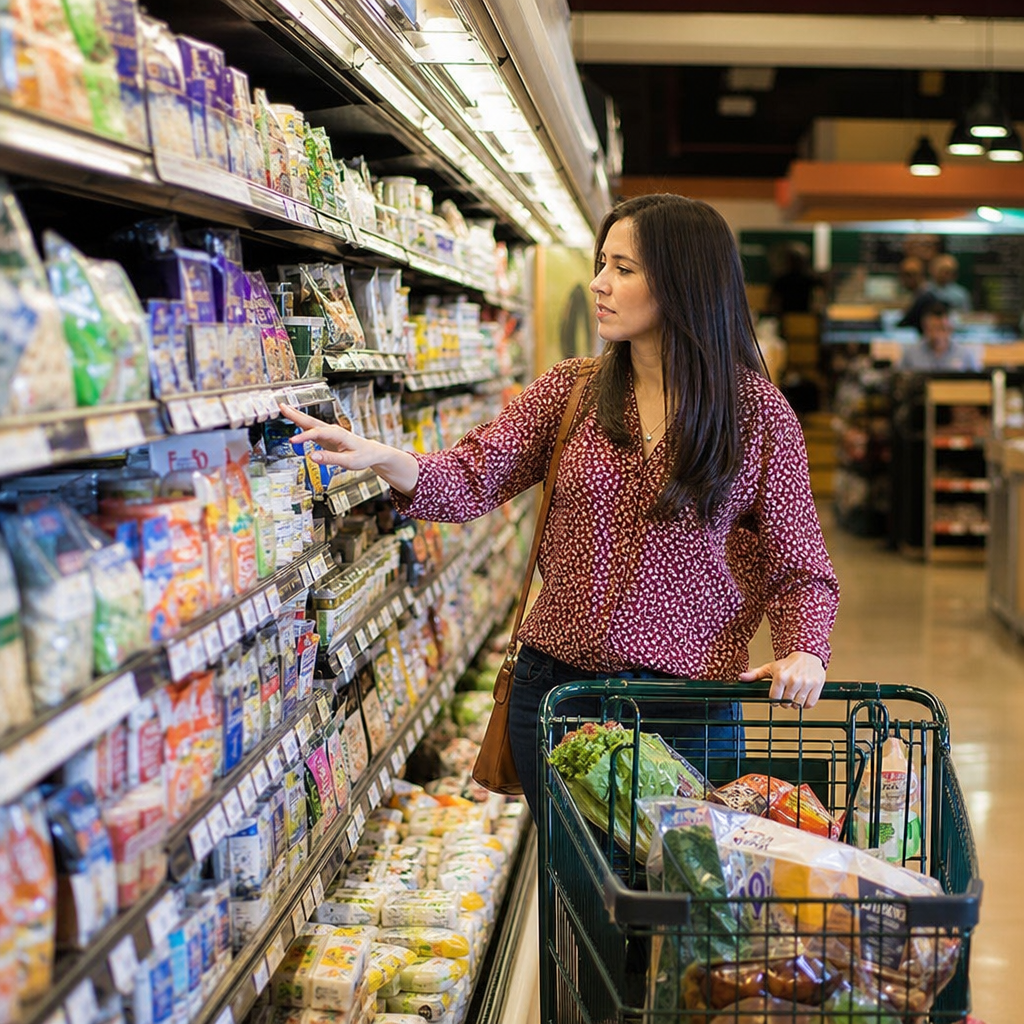
Consider a supermarket example. A household buys different combinations of cereal, milk, fruit, and snacks across twelve weeks. Prices change due to promotions, but income is roughly stable. Revealed preference analysis can test whether those purchases look consistent with a stable ranking of bundles. If consistency holds, the analyst can bound welfare changes from a price increase without guessing exact utility curves. If not, the analyst investigates causes: promotional salience, changing tastes, missing household inventory, or unobserved quality changes. The method is diagnostic as much as descriptive, which is why it has strong value in economics research.
Applications across economics and related fields
Consumer demand is the classic application, but revealed preference theory reaches much further. Labor economists use job choices and hours worked to infer tradeoffs between wages and leisure. Environmental economists study housing choices to estimate willingness to pay for clean air, school quality, or lower noise, a method related to hedonic pricing. Health economists infer risk preferences from insurance plan selections. Transport economists estimate values of travel time and reliability from route choices, toll lane usage, and mode switching between car, rail, and bus under changing fares and congestion.
In industrial organization, the framework helps interpret substitution patterns among products. When shoppers switch from a national brand to a private label after a price increase, that movement reveals competitive closeness more reliably than survey claims. Streaming services use viewing retention, upgrade paths, and cancellation behavior to infer which plan features matter most. In public finance, analysts evaluate whether tax credits or subsidies change revealed choices enough to justify program costs. Development economists use revealed preference tests on household surveys to assess whether consumption data are coherent before drawing welfare conclusions.
The broader “Misc” economics angle matters because this topic links many neighboring articles. Revealed preference theory is a bridge to utility theory, indifference curves, duality, elasticity, welfare economics, and household production. It also links to bounded rationality, prospect theory, and information economics because deviations from revealed preference consistency can indicate framing effects, uncertainty, or search frictions. In experimental economics, researchers compare laboratory choices with field behavior to see whether observed inconsistency reflects unstable preferences or artificial settings. As a hub concept, it organizes how economists move from choice data to substantive claims about value.
Strengths, criticisms, and modern extensions
The main strength of revealed preference theory is discipline. It relies on observed behavior, defined opportunity sets, and transparent consistency rules. That makes it less vulnerable to hypothetical bias than surveys and less dependent on arbitrary utility specifications than some structural models. It can generate welfare bounds even when exact preferences are unknown. It also travels well across contexts, from household consumption to online marketplaces. When I need a defensible first pass on what users truly value, revealed preference analysis is usually more credible than asking them directly, especially when money and time are at stake.
Critics, however, are right to note that choices do not reveal everything. A selected option may reflect habit, inattention, incomplete information, social pressure, or constraints not recorded in the dataset. If a parent buys a more expensive grocery basket, the reason may be shorter checkout lines, child preferences, dietary restrictions, or loyalty points unavailable to the researcher. Revealed preference can mislead when the analyst defines the choice set incorrectly. It also struggles when preferences genuinely change over time, which is common in health, education, and technology markets where learning alters valuation.
Modern economics therefore extends rather than abandons the framework. Behavioral revealed preference incorporates limited attention, present bias, and reference dependence. Random utility models allow probabilistic choice while retaining disciplined structure. Machine learning can improve prediction, but without revealed preference logic it often lacks welfare interpretation. The best current practice combines rich administrative or scanner data, careful institutional knowledge, and explicit consistency testing. Revealed preference theory remains indispensable because it forces economists to separate what data truly show from what they merely assume. For anyone studying economics, revisit your own market examples and examine what actual choices reveal.
Revealed preference theory turns everyday decisions into evidence about underlying values. By focusing on observed choices within real budget constraints, it gives economics a practical way to analyze demand, test rationality, and estimate welfare without leaning entirely on unverifiable statements about satisfaction. The central lesson is simple: what people do, when they could have done something else, contains structured information. Weak, strong, and generalized axioms formalize that idea, while Afriat’s Theorem and related tools make it usable with real data. That combination of conceptual clarity and empirical discipline explains the theory’s lasting importance.
As a hub topic within economics, revealed preference connects many subfields that are often taught separately. It supports consumer theory, pricing strategy, public policy evaluation, labor supply analysis, transportation research, and behavioral critiques of rational choice. Its strength is not that it claims people are perfectly consistent. Its strength is that it gives researchers a clear benchmark, a method for detecting departures from that benchmark, and a way to interpret tradeoffs carefully. When applied well, it improves both explanation and measurement, especially in markets where surveys and intuition routinely miss what choices reveal.
The practical takeaway is to look beyond what individuals, households, firms, or voters say they prefer and study the alternatives they actually choose under real constraints. That habit sharpens economic reasoning and leads to better analysis of prices, incentives, and welfare. If you are building out your understanding of economics, use this article as a starting point, then explore related topics such as utility theory, demand estimation, welfare economics, and behavioral economics to see how revealed preference shapes the wider field.
Frequently Asked Questions
What is revealed preference theory in simple terms?
Revealed preference theory is a way economists figure out what people value by looking at what they actually choose, rather than what they say they prefer. The central idea is straightforward: when a person faces several affordable options and picks one of them, that decision provides evidence about which option they rank more highly in that specific situation. For example, if a shopper can afford both apples and oranges but buys apples, that choice reveals that apples were preferred to oranges at those prices, with that budget, at that moment.
What makes the theory important is that it relies on observed behavior under real-world constraints. Preferences are not treated as abstract opinions alone; they are inferred from tradeoffs people are willing to make. Economists use this framework to study demand, test whether behavior appears consistent, and better understand how consumers respond to changes in income, prices, and available alternatives. In short, revealed preference theory turns choices into evidence about underlying preferences.
How does revealed preference theory differ from simply asking consumers what they want?
The key difference is that revealed preference theory focuses on actions rather than stated intentions. When people are surveyed, they may describe what they think they like, what they aspire to choose, or what sounds socially acceptable. But real decisions often look different once prices, budgets, time limits, and competing needs are involved. Revealed preference theory takes those constraints seriously and treats actual choices as more reliable indicators of what people are willing to prioritize.
This does not mean surveys and interviews are useless. Stated preferences can still help researchers understand motivations, expectations, or attitudes toward products and policies that do not yet exist. However, revealed preference has a major advantage: it is grounded in observed tradeoffs. If someone says they prefer healthy food but repeatedly buys cheaper convenience meals when both options are available, economists learn something important from the behavior itself. The theory is valuable precisely because it captures preferences as they appear in practice, not just in principle.
Why do economists care so much about consistency in choices?
Consistency matters because revealed preference theory is not just about identifying one isolated choice; it is about seeing whether a pattern of choices can be explained by a stable ordering of preferences. If a person chooses bundle A over bundle B when both are affordable, economists infer that A is at least as preferred as B in that context. But if that same person later chooses B over A when the situation suggests the opposite should happen, it raises questions about whether the choices can be reconciled with standard consumer theory.
To study this, economists use consistency conditions such as the weak and strong axioms of revealed preference. These tools help determine whether observed decisions fit the idea that people are making coherent choices according to some underlying preference ranking. This is useful because many economic models assume consumers behave in broadly consistent ways. If actual choices violate those assumptions, researchers may need to account for changing preferences, imperfect information, behavioral biases, or other real-world complications. So consistency is not a technical detail; it is central to connecting observed behavior with meaningful economic interpretation.
What are the main limitations of revealed preference theory?
Although powerful, revealed preference theory has important limits. First, it can only infer preferences from the options people actually face. If a person never had access to a certain product, price, or opportunity, their choices cannot reveal how they would rank that unseen alternative. Second, observed behavior may reflect more than pure preference. Habit, lack of information, social pressure, convenience, mistakes, or short-term stress can all influence decisions. In those cases, a purchase may not cleanly represent what a person values in a deeper or more stable sense.
Another limitation is that the theory usually works best when the context is clearly defined. A consumer may choose apples over oranges this week, but that does not mean apples are always preferred in every setting. Preferences can depend on price changes, income changes, health goals, seasonality, or what else is in the shopping basket. In addition, revealed preference does not always explain why someone chose an option; it mainly tells us that the chosen option ranked above the rejected ones among the affordable alternatives. That makes the theory extremely useful for analyzing behavior, but less complete when the goal is to uncover motives, emotions, or future intentions.
How is revealed preference theory used in real-world economics and business?
In economics, revealed preference theory helps researchers analyze consumer demand, evaluate whether behavior matches standard models, and estimate how people respond to changes in prices and income. For example, if households shift spending away from one category and toward another after a price increase, economists can use those observed substitutions to infer relative valuations. The theory also plays a role in welfare analysis, market design, and policy evaluation because it offers a disciplined way to connect actual decisions with underlying preferences.
In business, the same logic appears in customer analytics, pricing strategy, product design, and digital experimentation. Companies study what consumers click, buy, abandon, upgrade, or compare in order to learn what features and price points matter most. Streaming services infer viewing preferences from watch behavior, retailers infer price sensitivity from purchases and coupon use, and online platforms infer ranking and recommendation quality from engagement choices. In each case, the practical insight is the same: behavior under constraints reveals valuable information. While firms often combine this with survey data and demographic analysis, revealed preference remains one of the strongest tools for understanding what customers truly prioritize when they have to choose.