
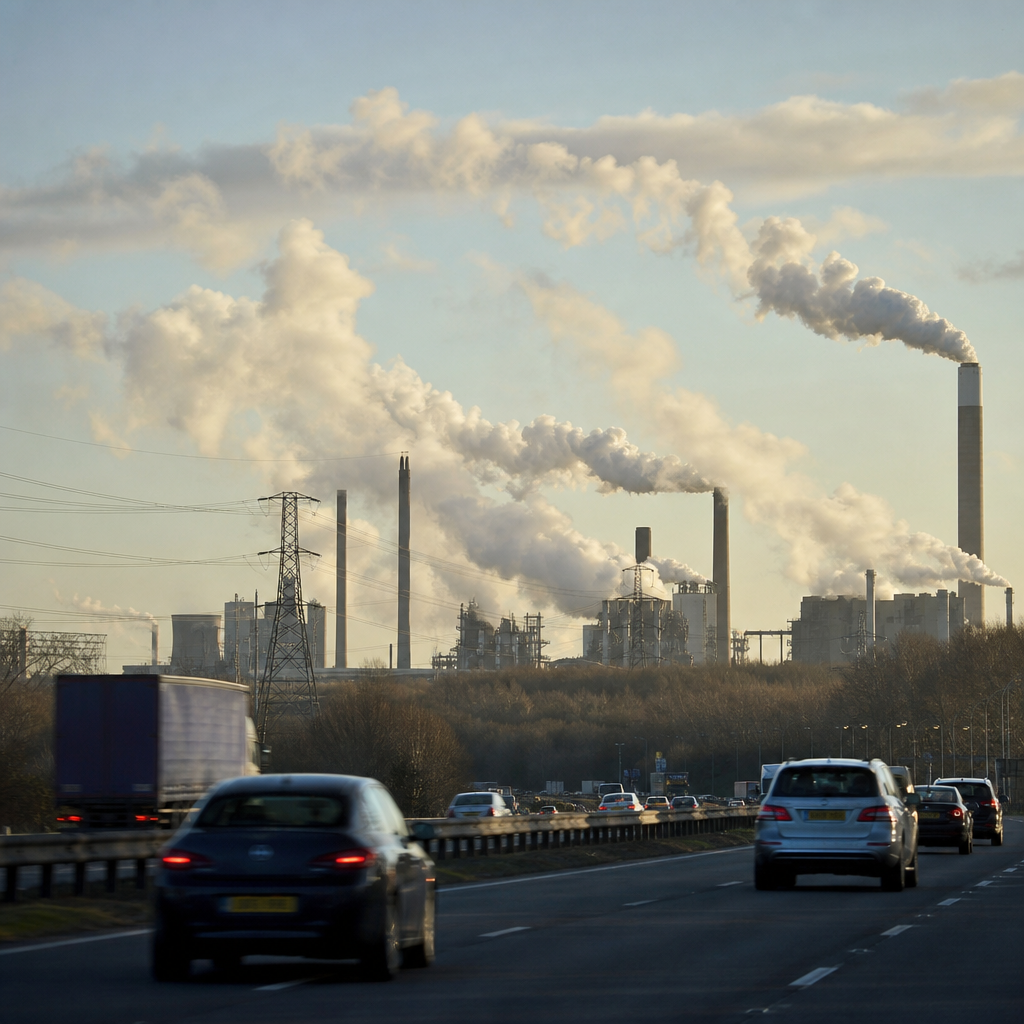
Pigouvian taxes are charges placed on activities that create external costs for other people, with the goal of making market prices reflect the full social cost of production or consumption. In economics, an externality exists when a transaction between a buyer and seller affects third parties who did not choose that transaction and were not compensated for the impact. Pollution is the standard example: a factory may earn profit and consumers may enjoy low prices, but nearby residents bear health risks, cleanup costs, and reduced quality of life. When those harms are left out of the price system, markets overproduce the harmful activity. A Pigouvian tax, named after economist Arthur Cecil Pigou, is designed to close that gap.
I have worked with policy teams and business operators evaluating environmental fees, congestion charges, and public health levies, and the same pattern appears repeatedly. If harmful side effects remain free, firms optimize around private cost only. Once a credible price is attached to the damage, decisions change fast: equipment upgrades move from “later” to “this quarter,” routes are redesigned, and consumers shift toward cleaner substitutes. That is why Pigouvian taxes matter beyond textbooks. They are one of the clearest ways to align private incentives with public welfare without dictating a single technology or banning an activity outright.
The key terms are straightforward but important. Marginal private cost is what the producer directly pays to make one more unit. Marginal external cost is the additional harm imposed on others from that extra unit. Marginal social cost equals the sum of the two. In an efficient market outcome, price should reflect marginal social cost, not just private cost. A correctly calibrated Pigouvian tax is set equal to the marginal external cost at the efficient level of output. In practice, exact calibration is difficult, but the principle remains powerful: when the price of a harmful activity rises to include its spillover damage, market participants reduce it to a more efficient level.
This topic sits at the center of economics because it connects welfare theory, public finance, environmental policy, transportation, energy, health, and urban planning. It also serves as a hub concept for many “miscellaneous” applications that do not fit neatly into one subfield. Carbon pricing, plastic bag charges, landfill fees, sugar-sweetened beverage taxes, tobacco excise taxes, road congestion pricing, noise charges near airports, and fertilizer runoff fees all involve the same core logic. Understanding Pigouvian taxes helps readers evaluate when a tax is correcting a market failure, when it is merely raising revenue, and how design details determine whether a policy actually works.
How Pigouvian Taxes Correct Externalities
A Pigouvian tax works by changing relative prices. If a coal plant imposes climate and health damages not reflected in its fuel bill, its electricity appears artificially cheap. Taxing emissions raises the plant’s effective cost and narrows the gap between private and social cost. Firms then respond in the way markets usually do: they cut output, adopt cleaner inputs, improve efficiency, or invest in abatement when doing so costs less than paying the tax. Consumers respond as well by reducing use or switching to alternatives. The policy does not require regulators to command exactly how the reduction happens. It lets decentralized choices discover the least-cost response.
The classic diagram shows marginal social cost above marginal private cost. The market equilibrium occurs where demand intersects private cost, creating excessive quantity. Add a per-unit tax equal to the external damage, and the supply curve shifts upward toward social cost. The new equilibrium has a higher price, lower quantity, and reduced deadweight loss from the externality. This is why economists often prefer corrective taxes to blunt quotas. A tax preserves flexibility. One factory may install scrubbers, another may change fuel mix, and another may shrink output; each chooses the cheapest path available.
This mechanism depends on incentives at the margin. A flat fine for being dirty does less than a charge on each unit of pollution, because the latter rewards every incremental reduction. That distinction matters in real regulation. Vehicle registration fees based only on ownership are less precise than fuel taxes tied to driving and emissions. Waste collection priced per bag gives households a direct reason to recycle and compost, while a fixed annual sanitation fee does not. When policymakers target the harmful unit itself, the tax becomes more efficient and easier for firms and households to understand.
Common Applications Across the Economy
The most prominent application is carbon pricing. A carbon tax places a fee on the carbon content of fossil fuels or on measured emissions, forcing emitters to account for climate damage that would otherwise remain off the balance sheet. Sweden’s carbon tax, introduced in 1991 and increased over time, is one of the best-known examples. Sweden combined the tax with broader energy and fiscal reforms and has managed substantial emissions reductions alongside economic growth. The lesson is not that every country can copy Sweden exactly; it is that long-run price signals can reshape investment, heating systems, transport choices, and industrial processes.
Congestion pricing applies the same logic to roads. Each additional driver entering a crowded corridor slows everyone else down, increasing travel time, fuel use, and local air pollution. Because those delay costs are external to the driver, peak-hour road use is overconsumed. London’s congestion charge, first launched in 2003, reduced traffic in the charging zone and improved travel reliability, especially in the early years. Singapore has gone further with electronic road pricing that varies by route and time. In my experience, transport agencies that explain congestion in terms of time lost per extra vehicle gain more public understanding than agencies that frame charges only as revenue tools.
Public health taxes also fit the model, though they are often more controversial. Tobacco excise taxes address secondhand smoke, public healthcare costs, and youth initiation. Alcohol taxes can partly offset drunk driving, violence, and healthcare burdens. Sugar-sweetened beverage taxes are usually defended on medical cost and information grounds, but here the externality case is weaker and more debated because much of the harm falls on the consumer. That does not make such taxes invalid; it means policymakers should be precise about their rationale. Corrective taxation is strongest where third-party harm is clear, measurable, and linked closely to the taxed activity.
| Application | Externality Targeted | Typical Tax Base | Observed Response |
|---|---|---|---|
| Carbon tax | Climate damage and local pollution | CO2 content of fuel or measured emissions | Fuel switching, efficiency upgrades, lower emissions |
| Congestion charge | Travel delay imposed on other drivers | Road entry, distance, time, or zone access | Peak travel reduction, route shifts, mode switching |
| Tobacco excise | Secondhand smoke and public health costs | Per pack or ad valorem sales tax | Lower consumption, reduced youth uptake |
| Landfill tipping fee | Waste disposal and land use impacts | Weight or volume of waste disposed | More recycling, composting, and waste diversion |
Local governments use many smaller versions. Landfill tipping fees discourage waste disposal and support diversion programs. Plastic bag charges reduce litter and marine pollution by increasing the visible cost of single-use bags at the point of sale. Airport noise charges can vary by aircraft type and time of day, creating incentives to use quieter fleets and schedule differently. Fertilizer and pesticide fees can address runoff into rivers and lakes, though measurement challenges often push agencies toward broader input taxes rather than direct pollution pricing. These examples show why Pigouvian taxes belong in a “miscellaneous” economics hub: the underlying concept travels across sectors with surprising consistency.
Design Choices That Determine Success
The most important design question is what exactly to tax. Economists prefer taxing the harmful output itself, such as tons of sulfur dioxide or carbon dioxide, because that directly prices the externality. When direct measurement is costly, governments use proxies. Fuel taxes approximate vehicle emissions and road use. Fertilizer taxes approximate nutrient runoff. A proxy can work well if the link between the tax base and the harm is strong, but weak proxies create distortion. If a fee is only loosely related to the damage, firms may reduce the taxed activity without meaningfully reducing the externality.
Rate setting is the next challenge. In theory, the tax should equal marginal external damage. In practice, that requires estimating health effects, environmental persistence, behavioral elasticity, technological options, and sometimes global damages discounted over decades. Policymakers rarely know the exact number. The best approach is to use the strongest available evidence, publish assumptions, and adjust gradually as data improves. Carbon pricing debates illustrate this clearly. Estimates of the social cost of carbon differ by discount rate, climate sensitivity, and damage function, yet that uncertainty is not a reason to price carbon at zero. It is a reason to build transparent review mechanisms.
Revenue use can shape both economic performance and political durability. Some governments return proceeds through lump-sum rebates, which can offset regressive effects on low-income households. Others cut distortionary taxes on labor or investment, seeking a broader efficiency gain. Still others earmark revenue for transit, clean energy, health programs, or local environmental remediation. Each approach has tradeoffs. Earmarking can build support but may reduce fiscal flexibility. Rebates can improve fairness but do not always preserve incentives if households view them as canceling the tax. From implementation work, I have found that simple, visible recycling of revenue often matters more for public acceptance than elegant theory alone.
Benefits, Limits, and Criticisms
The strongest argument for Pigouvian taxes is cost-effectiveness. By putting a price on harm and letting decentralized actors decide how to respond, they typically achieve reductions at lower total cost than uniform technology mandates. They also encourage innovation continuously. A command standard may lock in today’s best available technology, while a tax rewards any future method that reduces the taxed externality more cheaply. This dynamic effect is one reason economists have long favored emissions pricing for pollutants that can be measured reliably. The tax keeps paying firms to improve, year after year.
But corrective taxes are not magic. Measurement can be difficult, especially for diffuse harms like agricultural runoff or urban noise from many small sources. Administrative capacity matters. If emissions are underreported or if informal markets allow evasion, the theoretical efficiency of the tax will not show up in practice. Distributional concerns are also real. Energy and transport taxes can absorb a larger share of income for lower-income households, particularly where cleaner substitutes are limited. Rural households may face higher burdens than urban households if public transit is scarce. Good policy acknowledges these realities and builds compensation or transition support into the package.
There are also cases where taxes should be paired with other tools. Information failures, market power, infrastructure gaps, and behavioral biases can weaken the response to price signals. For example, tenants may pay utility bills while landlords choose insulation and heating systems, creating a split incentive. In that case, building codes or retrofit programs may complement energy taxes. Likewise, if consumers underestimate long-term fuel savings, efficiency labeling may reinforce a gasoline tax. The practical lesson is not “taxes versus regulation.” It is “use the price where it fits best, and supplement it where markets still fail for other reasons.”
Critics sometimes argue that governments will use Pigouvian taxes as disguised revenue grabs. That risk exists, and economists should admit it plainly. A tax called corrective is not automatically well designed. The test is whether the tax base tracks the harm, the rate reflects evidence, and the broader policy package addresses fairness and enforcement. Another criticism is that some externalities involve moral judgments, not just measurable costs. That is true for issues like gambling, unhealthy food, or certain vice taxes. In those areas, analysts should separate paternalistic aims from true third-party harms rather than collapsing them into one category.
How to Evaluate a Pigouvian Tax in Practice
When assessing whether a proposed tax is genuinely corrective, start with five questions. First, what is the externality, and who bears it? Second, can the harm be measured directly or only through a proxy? Third, how sensitive are producers and consumers to price changes? Fourth, what alternatives do they have? Fifth, how will the revenue be used, and who ultimately bears the burden? These questions turn abstract theory into operational analysis. They also help readers compare policies across the broader economics landscape, from environment to health to local public finance.
Evidence should come from observed behavior, not just model assumptions. Look for natural experiments, cross-jurisdiction comparisons, and before-and-after administrative data. For example, studies of plastic bag charges often find large immediate reductions in single-use bag consumption because the fee is salient at checkout and substitutes are obvious. By contrast, broad electricity taxes may generate slower responses where appliances and heating systems are durable capital stock. Time horizon matters. Short-run demand can be inelastic, while long-run adaptation can be substantial once vehicles, boilers, machinery, and buildings are replaced.
The best Pigouvian taxes are legible. People understand what is being charged, why it is being charged, and how to reduce the bill. That clarity improves compliance and strengthens the incentive effect. If you are building an economics reading list or policy framework, use Pigouvian taxation as a hub concept linking environmental economics, public choice, cost-benefit analysis, tax incidence, and behavioral economics. It is one of the few ideas that moves cleanly from theory to practice. Review the externality, inspect the tax base, follow the incentives, and judge the results against measurable social costs.
Frequently Asked Questions
What is a Pigouvian tax, and why do economists use it to address externalities?
A Pigouvian tax is a tax placed on an activity that creates negative external costs for people who are not part of the original transaction. The central idea is straightforward: when a market price reflects only the private costs paid by buyers and sellers, it can encourage too much of an activity that also harms others. Economists use Pigouvian taxes to bring those hidden social costs into the price, so the market outcome better reflects the true cost to society.
Pollution is the classic example. A factory may pay for labor, materials, equipment, and transportation, but if it also releases emissions that damage health, reduce property values, or harm ecosystems, those costs are often borne by nearby residents rather than the factory itself. In that case, the product being sold is artificially cheap because part of its cost has been shifted onto third parties. A Pigouvian tax attempts to correct that distortion by charging the polluter an amount tied to the damage created.
In practical terms, this changes incentives rather than banning market activity outright. Firms and consumers can still make choices, but now they must account for a fuller cost of those choices. That can lead to less harmful production, cleaner technology, or reduced consumption of damaging goods. For economists, this is appealing because it preserves flexibility while improving efficiency. Instead of relying only on rigid rules, a Pigouvian tax uses the price system itself to guide behavior toward a more socially optimal outcome.
How does a Pigouvian tax change behavior in markets?
A Pigouvian tax works by increasing the private cost of an activity that creates harm for others. Once the tax is added, producers and consumers see a higher effective price, which influences decisions throughout the market. Producers may reduce output, invest in cleaner processes, redesign products, or switch to less harmful inputs. Consumers may buy less of the taxed good, seek substitutes, or alter how they use it. The point is not simply to raise revenue; it is to change incentives so that market participants internalize the external cost.
Consider a factory that emits pollution while manufacturing a low-cost product. Before the tax, the factory decides output based mainly on its own costs and expected profits. If a tax is imposed on emissions or on each unit of pollution-intensive production, the factory now faces a direct financial consequence for the harm it creates. This makes pollution reduction more valuable. If installing cleaner equipment costs less than continuing to pay the tax, the firm has a strong reason to innovate. If reducing production is the cheaper option, output may fall. Either way, the tax encourages behavior that better aligns private incentives with social well-being.
Markets respond through both quantity and technology. Some firms will cut back, others will adapt, and the least efficient polluters may exit. Consumers also respond to higher prices by changing purchases. Over time, this can produce a broad shift toward cleaner goods and methods. One reason Pigouvian taxes are often praised is that they allow each market participant to determine the lowest-cost way to respond, which can make them more efficient than one-size-fits-all regulations.
How is the “right” level of a Pigouvian tax determined?
In theory, the ideal Pigouvian tax equals the marginal external cost of the harmful activity. That means the tax should match the additional damage imposed on others by producing or consuming one more unit of the good. If the tax is set at that level, the market price will reflect both private and external costs, and the resulting quantity should move closer to the socially efficient outcome.
In reality, calculating that number is difficult. External harms can be complex, diffuse, and uncertain. Pollution, for example, may affect air quality, public health, agricultural productivity, biodiversity, and long-term climate conditions. Those effects may vary by location, timing, and population exposure. Economists and policymakers therefore rely on scientific evidence, health studies, environmental modeling, cost estimates, and sometimes informed approximations to determine a reasonable tax rate.
Because perfect measurement is rarely possible, Pigouvian taxes are often designed as practical policy tools rather than mathematically exact solutions. Governments may start with a moderate rate and adjust it over time as better data becomes available. They may also target a measurable proxy, such as carbon content, emissions volume, or waste output. Even when the tax is not perfectly calibrated, it can still improve incentives compared with leaving the externality completely unpriced. The key principle is that the tax should be meaningfully connected to the harm created, so that the price signal guides behavior in the right direction.
What are the advantages and criticisms of Pigouvian taxes compared with direct regulation?
The main advantage of a Pigouvian tax is efficiency. Instead of telling every firm exactly what technology to use or how much to reduce emissions, the tax lets each actor decide how to respond based on its own costs and opportunities. Firms that can cut pollution cheaply will do so quickly, while firms with higher reduction costs may pay the tax in the short run and adjust later. This flexibility tends to lower the overall cost of reducing harm across the economy.
Another major benefit is that Pigouvian taxes encourage continuous improvement. A fixed regulation may require firms to meet a standard and stop there, but a tax creates an ongoing incentive to reduce harmful activity further whenever doing so becomes cheaper than paying the tax. That can promote innovation, cleaner production methods, and the development of better substitutes. In many cases, the tax also generates government revenue that can be used to reduce other taxes, fund public services, or compensate communities most affected by the externality.
That said, Pigouvian taxes face several criticisms. One common concern is measurement: if policymakers cannot estimate the true external cost accurately, the tax may be set too high or too low. Another issue is politics. Taxes are often unpopular, and lobbying can distort design or implementation. There are also equity concerns, since higher prices can fall more heavily on lower-income households unless revenue is used thoughtfully. Finally, some harms may be so severe or irreversible that taxation alone is not enough, making direct regulation, standards, or bans more appropriate. In practice, many economists view Pigouvian taxes and regulation as complements rather than mutually exclusive alternatives.
What are some real-world examples of Pigouvian taxes, and do they actually work?
Real-world policies inspired by Pigouvian logic include carbon taxes, gasoline taxes, congestion charges, taxes on cigarettes, and fees on plastic bags or landfill waste. Each of these aims to account for costs that private decision-makers might otherwise ignore. Carbon taxes, for example, are designed to reflect the climate damage associated with greenhouse gas emissions. Congestion pricing charges drivers for using crowded roads at peak times, recognizing that one more car slows everyone else down. Cigarette taxes are often justified partly by the healthcare costs and secondhand smoke harms imposed on others.
These policies can work well when they are carefully designed, broadly applied, and supported by clear monitoring. Evidence from many settings shows that higher prices do reduce harmful behavior. Fuel taxes tend to reduce fuel consumption and encourage more efficient vehicles. Congestion charges have lowered traffic volumes and improved travel times in major cities. Taxes on disposable bags have reduced bag usage significantly in many jurisdictions. The response may not be immediate or dramatic in every case, but pricing harmful activities usually changes incentives in the intended direction.
Their success, however, depends on details. If the tax is too small, behavior may barely change. If there are easy ways to evade it, the policy loses effectiveness. If substitutes are not available, adjustment may be slow. Public acceptance also matters. People are more likely to support these taxes when the purpose is transparent and the revenue is used well, such as funding public transit, reducing other taxes, or helping households adapt. So yes, Pigouvian taxes can work, but they work best as part of a well-designed policy framework grounded in credible evidence and clear economic reasoning.